The Weekly: Markets Await Their Next Catalyst
NOV 9, 2026
Post-midterm selloff gives Nasdaq its worst day since 2020, yet the AI trade holds. Bitcoin tests $73k–$75k support as crypto awaits looser liquidity.
New Institutional Report, written in collaboration with Clear Street. Institutional DeFi needs a common language for risk. Led by Re7 Founder and CIO Evgeny Gokhberg and built on our own methodology, A Framework for Decomposing DeFi Risk in the Age of AI breaks exposure into chain, protocol and asset layers and explores how AI is reshaping risk monitoring.
Evgeny Gokhberg joined Alex Scott on Solana is Global “How Re7 Turned On-Chain Risk Into a Repeatable Investment Process”
🎧 Spotify
🍎 Apple
Stablecoins beyond payments: Ethena Labs's Guy Young on Crypto Minutes, Bloomberg TV
Re7’s Founder & CIO Evgeny Gokhberg hosts Guy Young, Founder & CEO of Ethena Labs, on how Ethena is building a full financial platform around stablecoins.
“The core idea behind our product was a savings product and a digital dollar that anyone in the world could access with just an internet connection, in order to spend, save and send on crypto rails.”
Watch the full episode here.
We are hiring!
Senior Legal Counsel - Apply here.
Crypto Fund Operations Manager - Apply here.
Weekly Summary
We cover:
The impact of the midterms and tight financial conditions on markets
Why the AI trade remains fundamentally intact
Key technical support levels across crypto and what could reverse momentum
Markets Await Their Next Catalyst
The Midterms and the Liquidity Constraint
The US midterms proved to be the clearing event markets had been anticipating.
After an initial risk-off reaction, markets rallied sharply into the early hours of Wednesday morning, helped by hedge funds covering positions following aggressive de-risking into the election.
The rally subsequently faded as investors reassessed the implications of Democratic gains for the AI trade, particularly the prospect of greater political and regulatory friction.
The reversal culminated in the Nasdaq-100 falling 6.35% on Thursday, its worst single-day decline since the COVID crash in March 2020.
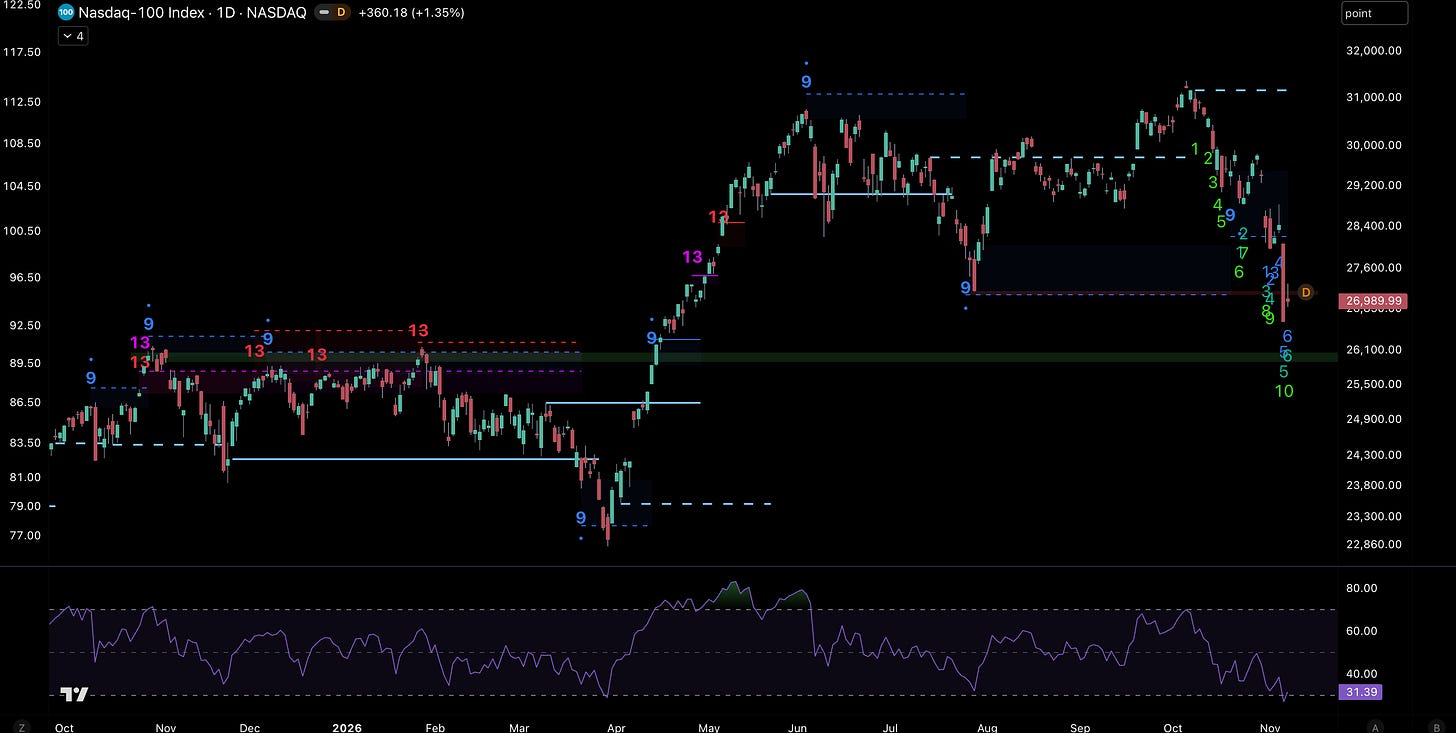
Now, L/S funds gross leverage are at the 0-th percentile. Selling of global AI stocks hit 3 SD extreme. Fear gauge now at 9.6/10.
Yet, despite the severity of the selloff, there are few signs of selling exhaustion or outright capitulation (incl. NDX, Mag7, semis, KOSPI etc), leaving markets still searching for a bottom in the near-term.
At the same time, relatively little attention has been paid to the more persistent constraint on risk assets: liquidity.
Higher front-end rates, a stronger dollar and elevated oil prices have kept financial conditions tight, with persistent inflation concerns leading markets to price further rate hikes. Any progress towards a deal with Iran could materially change the outlook for oil and inflation.
The 12-month rate of change in financial conditions has historically led the Nasdaq by approximately three months, and the relationship continues to track closely…
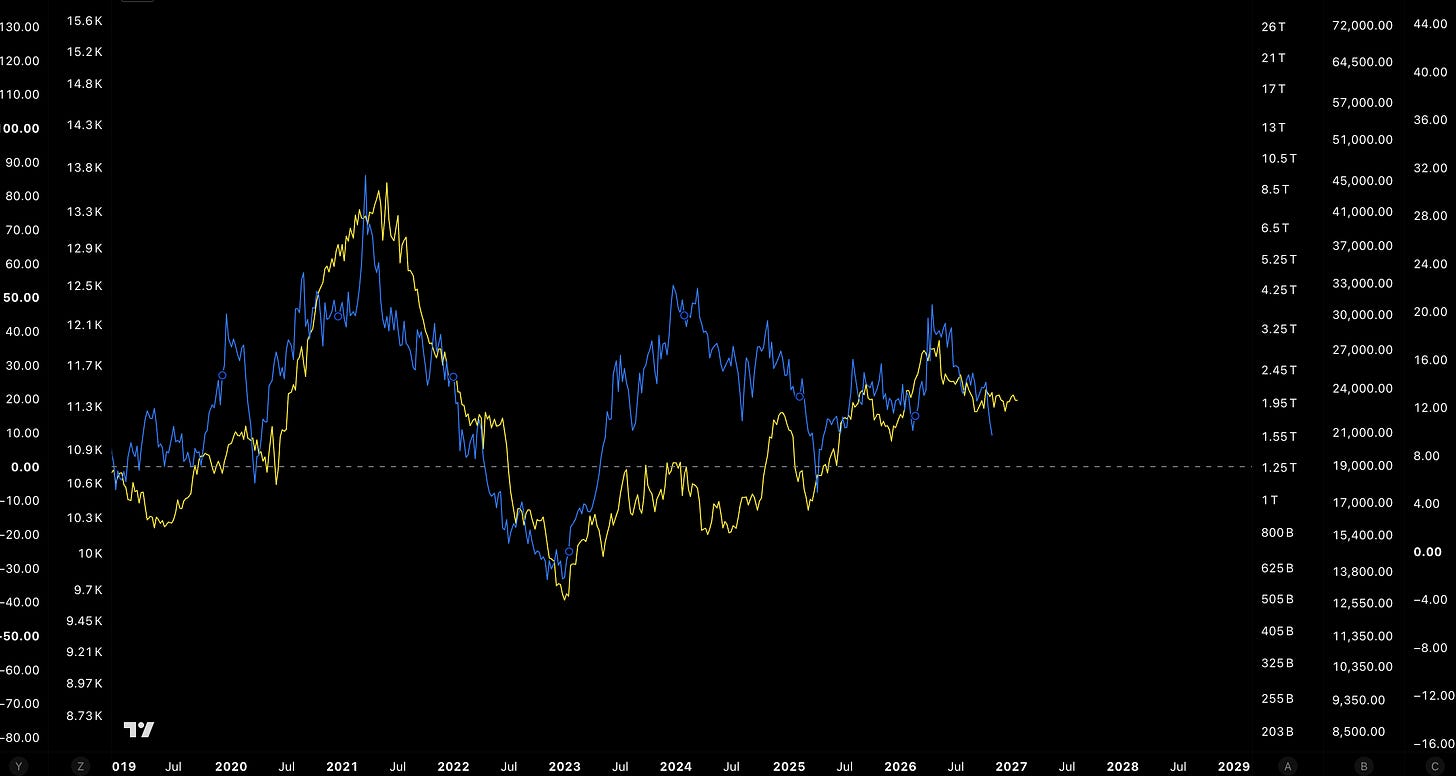
The deterioration in financial conditions helps explain the recent loss of momentum in technology and crypto, with a sustained recovery likely requiring some relief in rates, dollar, oil, inflation etc.
In other words, we know what needs to happen for confidence to get restored at these record de-leveraging events. And hence why the market is finding its bottom and anticipating its next move.
The AI Trade Remains Intact
Despite recent weakness, we see little evidence of a fundamental breakdown in the AI trade.
The major hyperscalers have maintained their capital expenditure commitments, with no meaningful indication that the underlying investment cycle is slowing. Bipartisan senate bills on AI buildout could be as early as this week.
Credit markets also remain relatively orderly.
High-yield credit has weakened, although conditions remain far from the stress observed in Q1 2026. Investment-grade credit has been more resilient, with spreads still below their 2nd November peak.
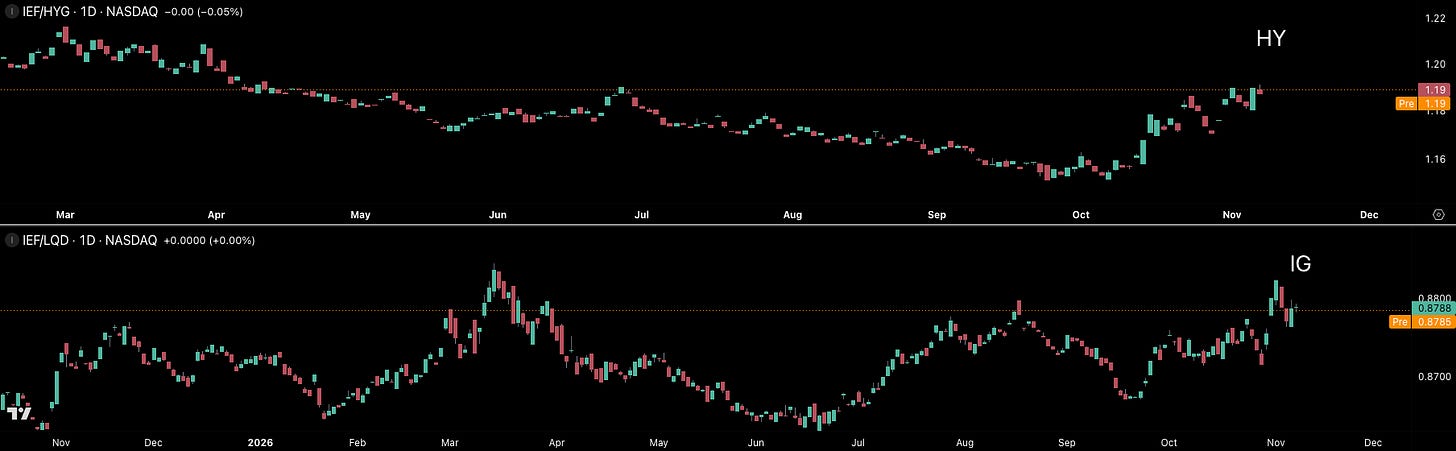
The distinction matters given how much of the broader risk-on trade, including crypto, continues to depend on confidence in AI investment.
With oil prices and front-end rates beginning to ease, there is still scope for financial conditions to improve and support another leg higher.
Crypto at Key Support
Crypto has also stopped losing ground against US technology, with the crypto/Nasdaq ratio stabilising in recent weeks following a prolonged period of underperformance.
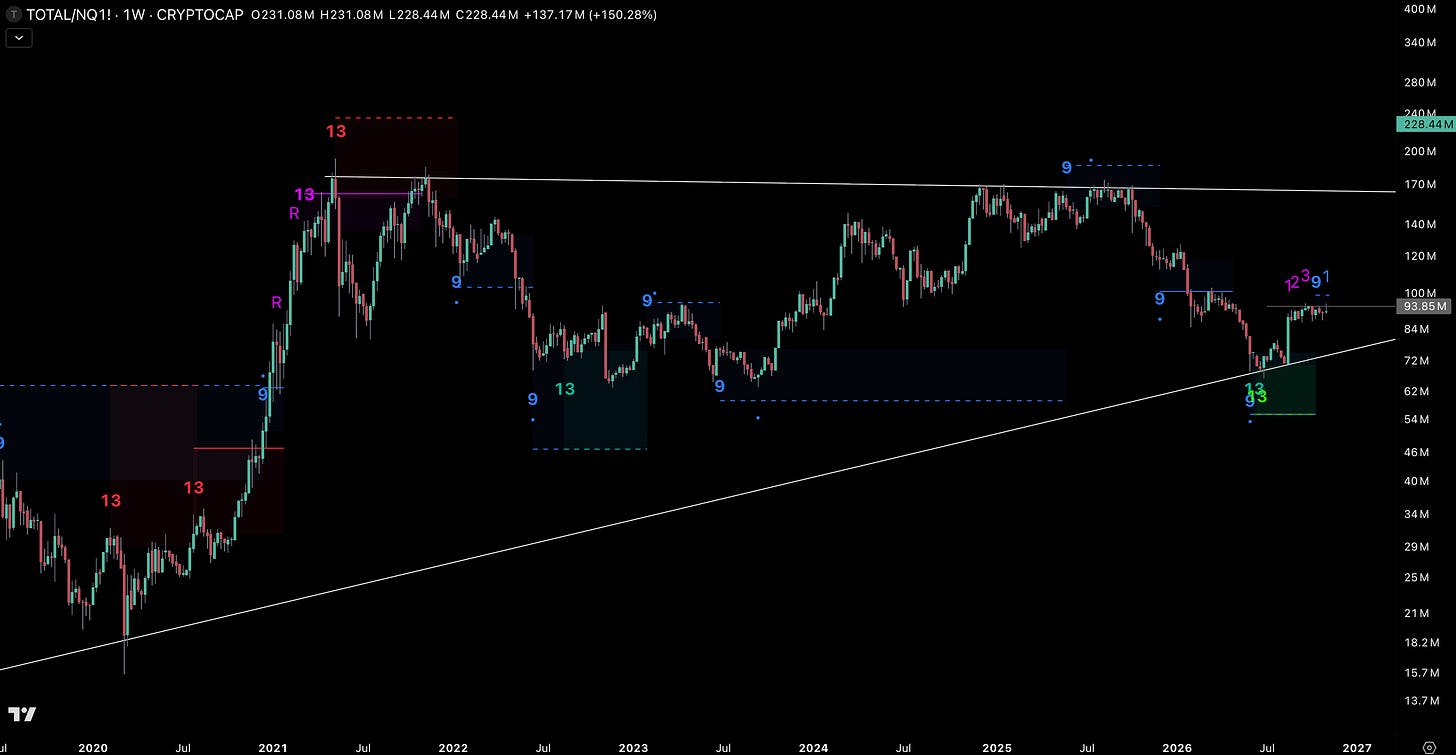
We see crypto and AI as part of the same exponential technology trade, with both dependent on liquidity and looser financial conditions as the underlying driver of risk appetite.
Crypto is therefore awaiting direction alongside the AI trade, with the next sustained move likely to depend on whether financial conditions begin to ease.
Bitcoin is once again challenging its 50-week moving average, currently around $75k.
The 200-week moving average sits close below at $73k, creating a relatively narrow support zone between the two levels.
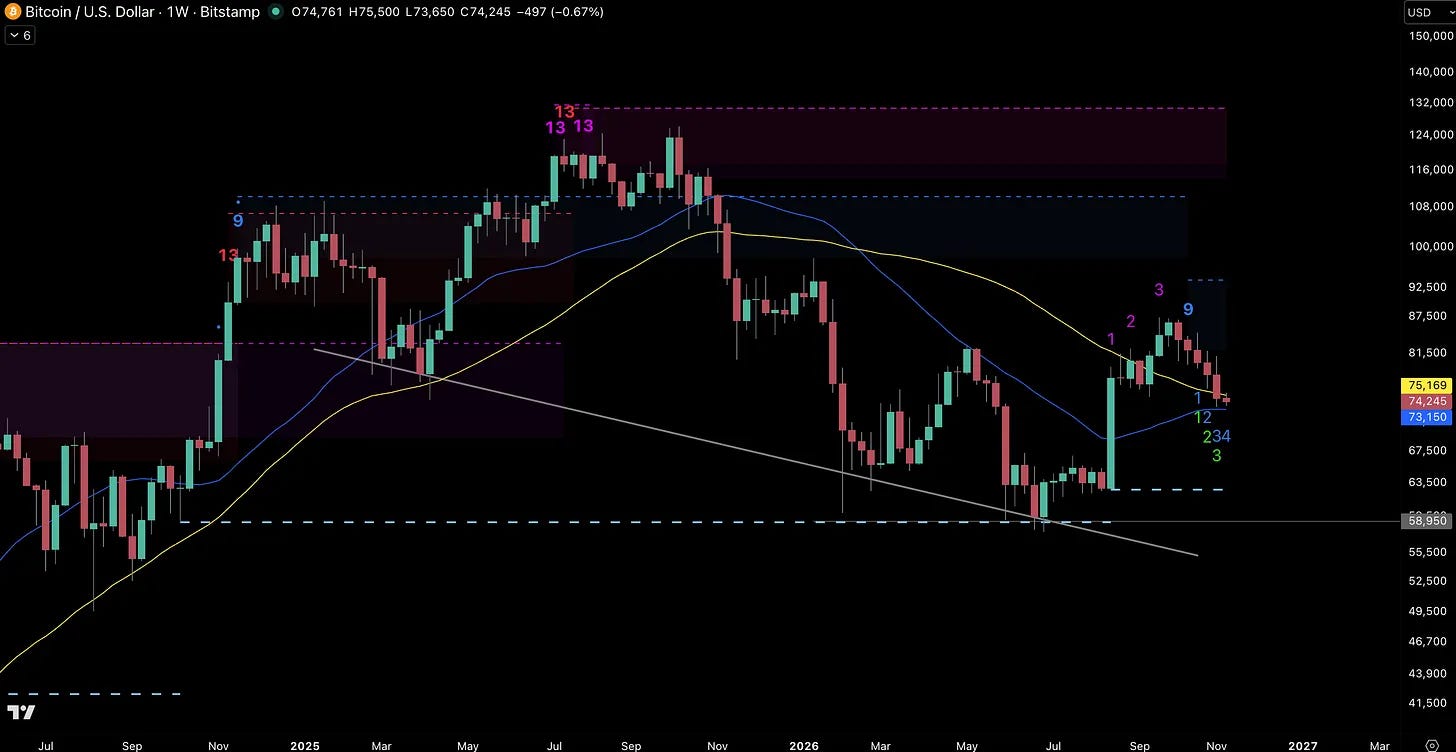
If selling momentum overwhelms the area, the next meaningful support comes from the summer lows around $62.6k and $57.7k.
Solana is similarly approaching a significant technical level, trading near its five-year ascending trendline.
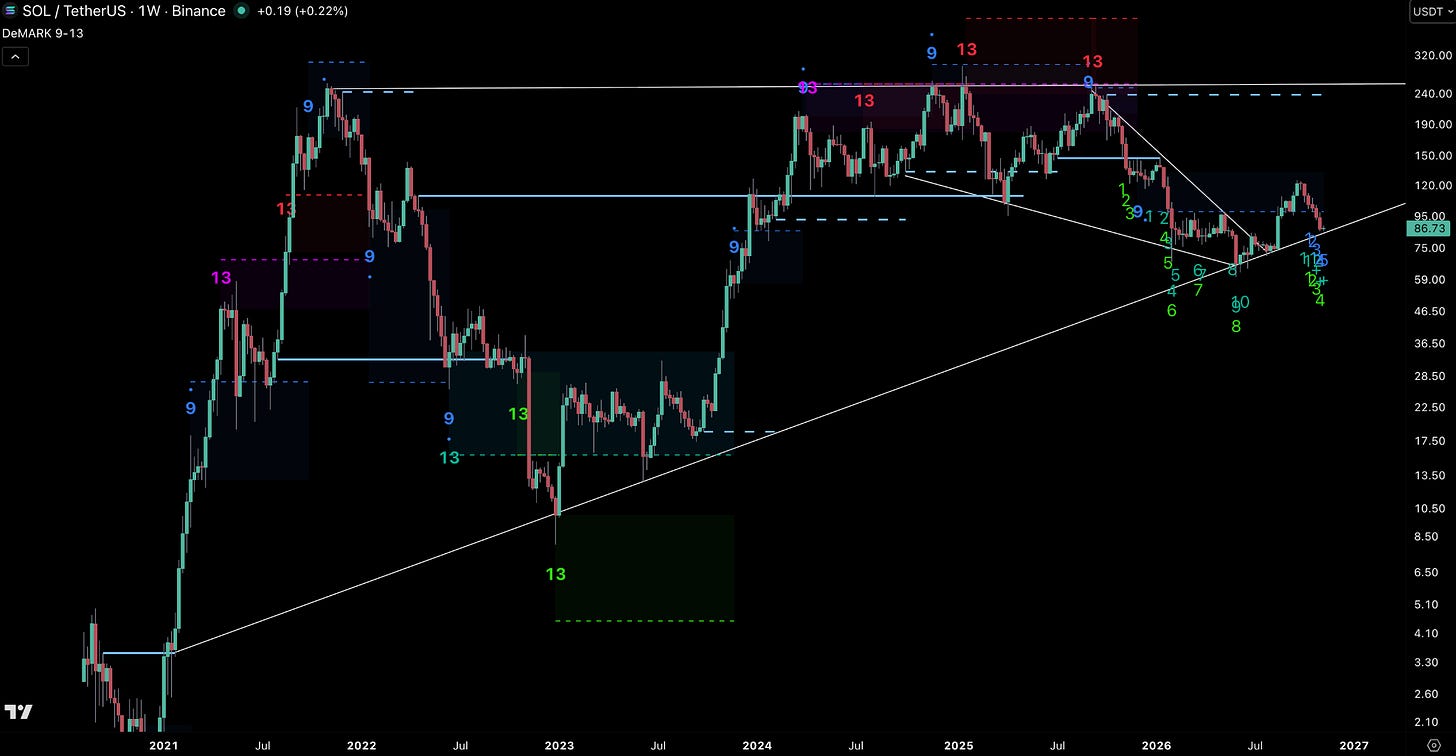
The opportunity extends beyond large-cap L1s.
Alts relative to Bitcoin are approaching some of their most attractive levels since May 2026, returning to a well-established support area following months of underperformance.
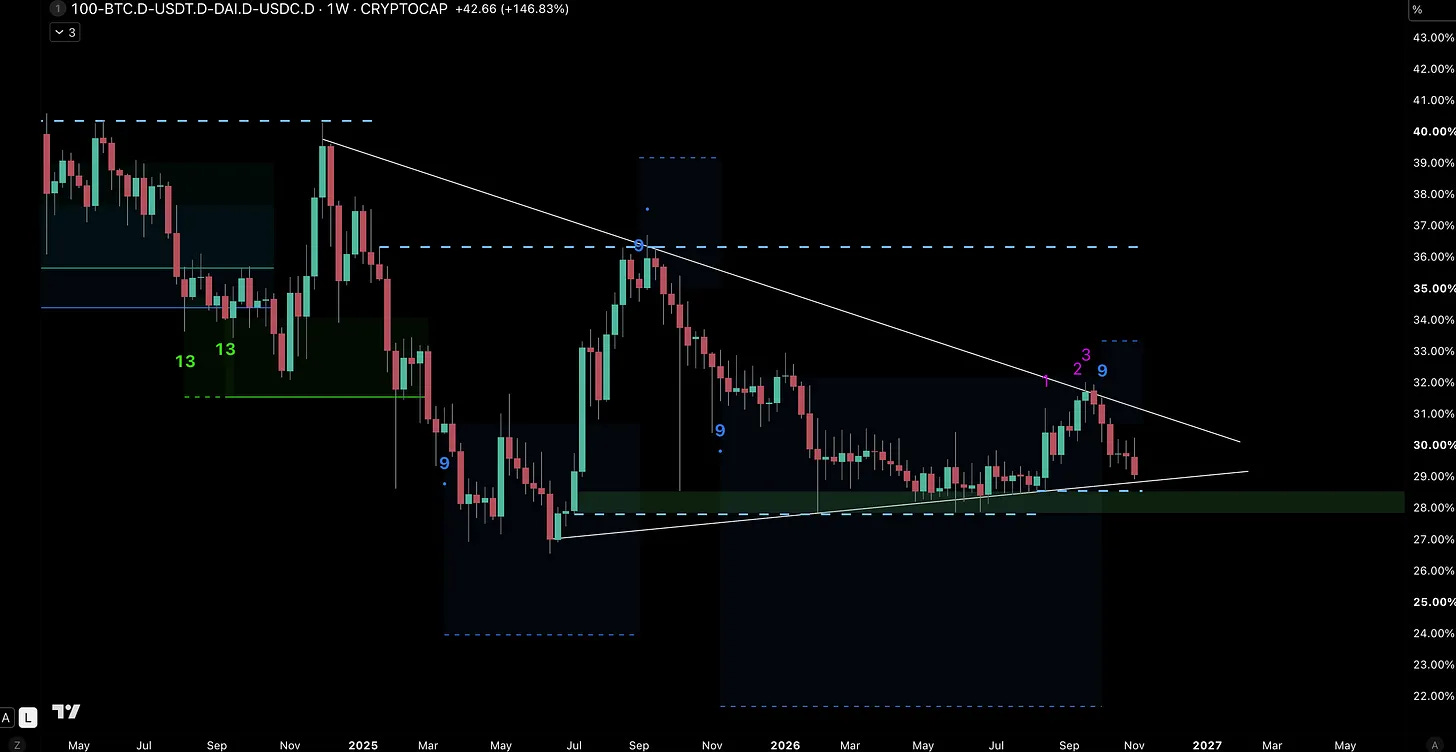
The broader altcoin market is also holding its long-term rising trendline, with recent downside momentum beginning to stabilise.
The convergence of support across Bitcoin, Solana and the broader altcoin market leaves crypto at an important inflection point.
Waiting for Momentum to Turn
For now, crypto has been trading broadly in line with the AI trade, with both markets awaiting direction from liquidity and financial conditions.
We continue to see the recent correction as primarily driven by tight financial conditions and positioning, rather than a fundamental deterioration in the AI investment cycle.
Oil prices have begun to retreat and financial conditions are showing early signs of stabilisation, although front-end rates remain restrictive. A sustained decline in the dollar and short-term yields would provide further relief.
With crypto approaching major technical support and credit markets showing little evidence of systemic stress, even the first signs of improving liquidity conditions could be enough to reverse the recent momentum.
State of Yields
Yields have expanded slightly across the board in light of recent market volatility:
Stablecoin lending yields:
~3.77% on Aave (USDC) — 10 bps higher than last week.
~4.50% on Aave (USDe) — 16 bps lower than last week.
~5.14% on Maple (syrupUSDC) — 2 bps lower than last week.
Fixed-rate DeFi lending: yield premium in fixed markets:
Pendle sUSDAi: ~9.1% (Oct 2026 – Feb 2027 maturities).
sUSDe: ~5.14% —30 bps lower than last week.
ETH yield benchmarks:
Lido staking: ~2.74% — 50 bps higher than last week.
About Re7
Re7 Capital is a research-driven digital asset investment firm specialising in DeFi yield and liquid alpha strategies.
Re7 Labs is an on-chain asset management and risk curation firm bringing institutional-grade rigour to DeFi.
Disclaimers
The content is for informational purposes only. None of the content is meant to be investment advice. Use your own discretion and independent decision regarding investments. The opinions expressed in all Re7 public research articles are the independent opinions of the authors at the time of publication and not the opinions of the affiliates of Re7.
Please see here for full disclaimers.
Thanks for reading Re7 Research! Subscribe for free to receive new posts and support our work.