The Weekly: Markets Are Refusing to Break
OCT 19, 2026
Crypto markets are refusing to break. Bitcoin keeps finding buyers around $80,000 despite Brent crude near $105, hotter-than-expected US CPI and PPI, and AI financing concerns after CoreWeave’s sell-off. Sentiment has fallen to Extreme Fear even though total crypto market cap is only 7% below its September peak, and crypto outperformed the Nasdaq 100 by more than 2% last week. Looking ahead, we cover China’s Q3 GDP beat, hyperscaler earnings and the 3 November US midterms as possible catalysts into year-end, plus this week’s DeFi yields across Aave, Maple, Pendle, Ethena and Lido.
Re7 Celebrates 5 Years. In recognition, The Hedge Fund Journal featured Re7 Capital. Read the full profile to find out how we think about risk in DeFi, and why we treat it closer to a credit discipline than a trading strategy.
Evgeny Gokhberg joined 1000x Podcast: What It’s Like Running A Billion-Dollar Market-Neutral Fund In Crypto.
Bloomberg TV: Beyond Holding ETH: Sharplink on Crypto Minutes.
Evgeny Gokhberg speaks with Joseph Chalom, CEO of Sharplink, on how a Nasdaq-listed Ethereum treasury goes beyond holding ETH, combining price exposure with active, professional management of its asset base.
“We have an in-house capability to do 80 to 90 percent of the work ourselves, but we also have the ability to pick the right managers, and working with people like Re7 Capital allows us to extend our capabilities...”
Watch the full episode here.
We are hiring!
Senior Legal Counsel — Apply here.
Crypto Fund Operations Manager - Apply here.
Re7 Labs
Re7 Labs has launched a Frax USDai Ecosystem Vault on Mainnet with Frax Finance and USD.AI, deploying frxUSD across curated opportunities in the USDai ecosystem.

Weekly Summary
We cover:
Why Bitcoin is absorbing negative macro headlines
The growing disconnect between sentiment and price
What could drive the next leg higher into year-end
Markets Are Refusing to Break
Crypto markets are refusing to break, finding clear support above $80k, around early September highs.
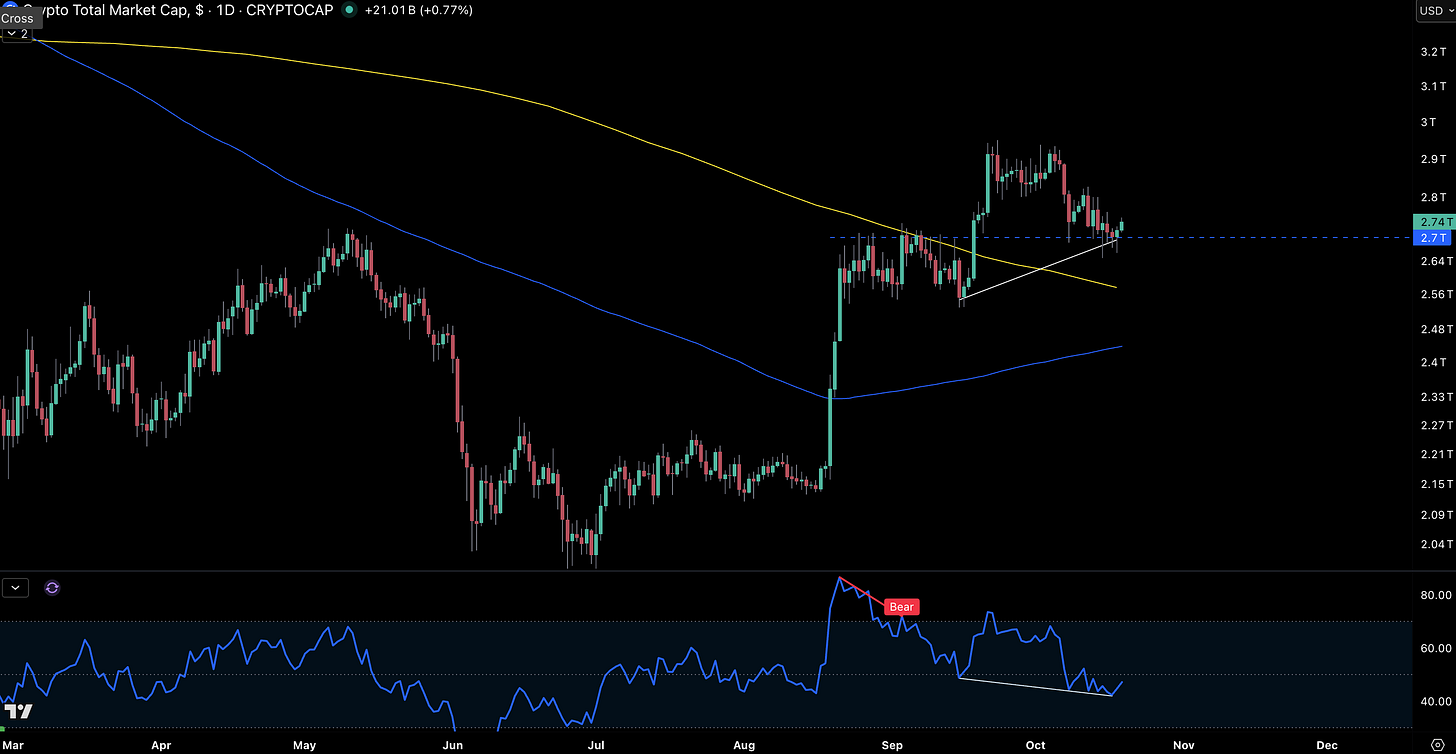
Global crypto market capitalisation index ($; daily).
Markets have had plenty of reasons to sell over the past two weeks.
Brent crude surged towards $105, US CPI and PPI surprised to the upside, and concerns over AI financing intensified following CoreWeave’s sell-off.
Each would ordinarily weigh on risk assets through higher inflation, tighter monetary policy or weaker growth expectations.
Yet Bitcoin has repeatedly found buyers around $80,000, with little sustained downside despite these headwinds.
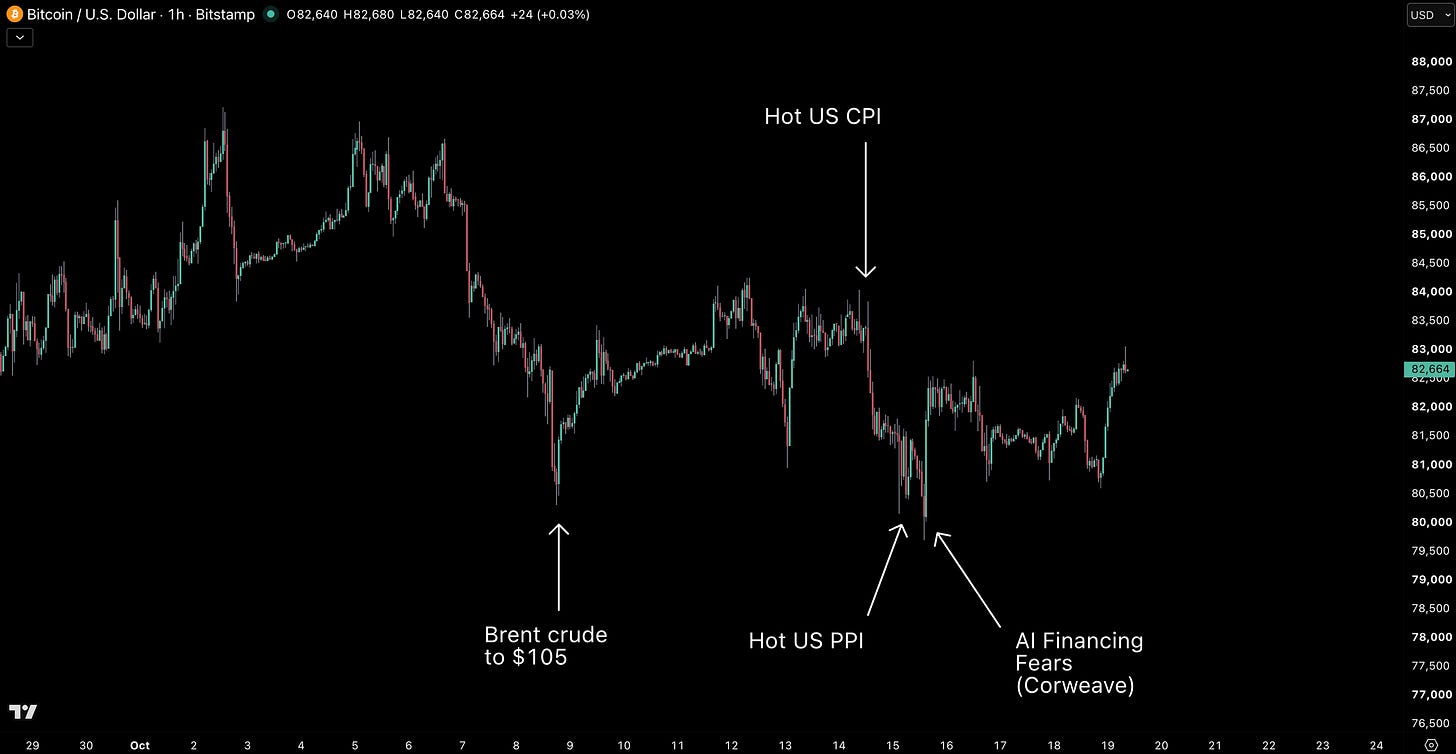
BTC/USD. Bitcoin holds firm despite negative macro headlines.
This is particularly constructive following Bitcoin’s breaks below its 200-day and 50-week moving averages, both traditionally bearish momentum signals.
When negative news and bearish technicals fail to push prices materially lower, it suggests sellers are becoming exhausted. This is characteristic of bull market behaviour.
Nasdaq futures are also up >1% this morning, with AI stocks rebounding strongly and further evidence that sellers are struggling to sustain downside momentum.
Sentiment Is Pricing In a Correction That Hasn’t Happened
The disconnect between sentiment and price is becoming increasingly pronounced.
Since sentiment peaked on 21 September, total crypto market capitalisation has declined just 7%, while Fear & Greed has fallen 38% on an indexed basis.
On 4 October, market capitalisation had returned to its September peak, yet sentiment was already 11% lower.
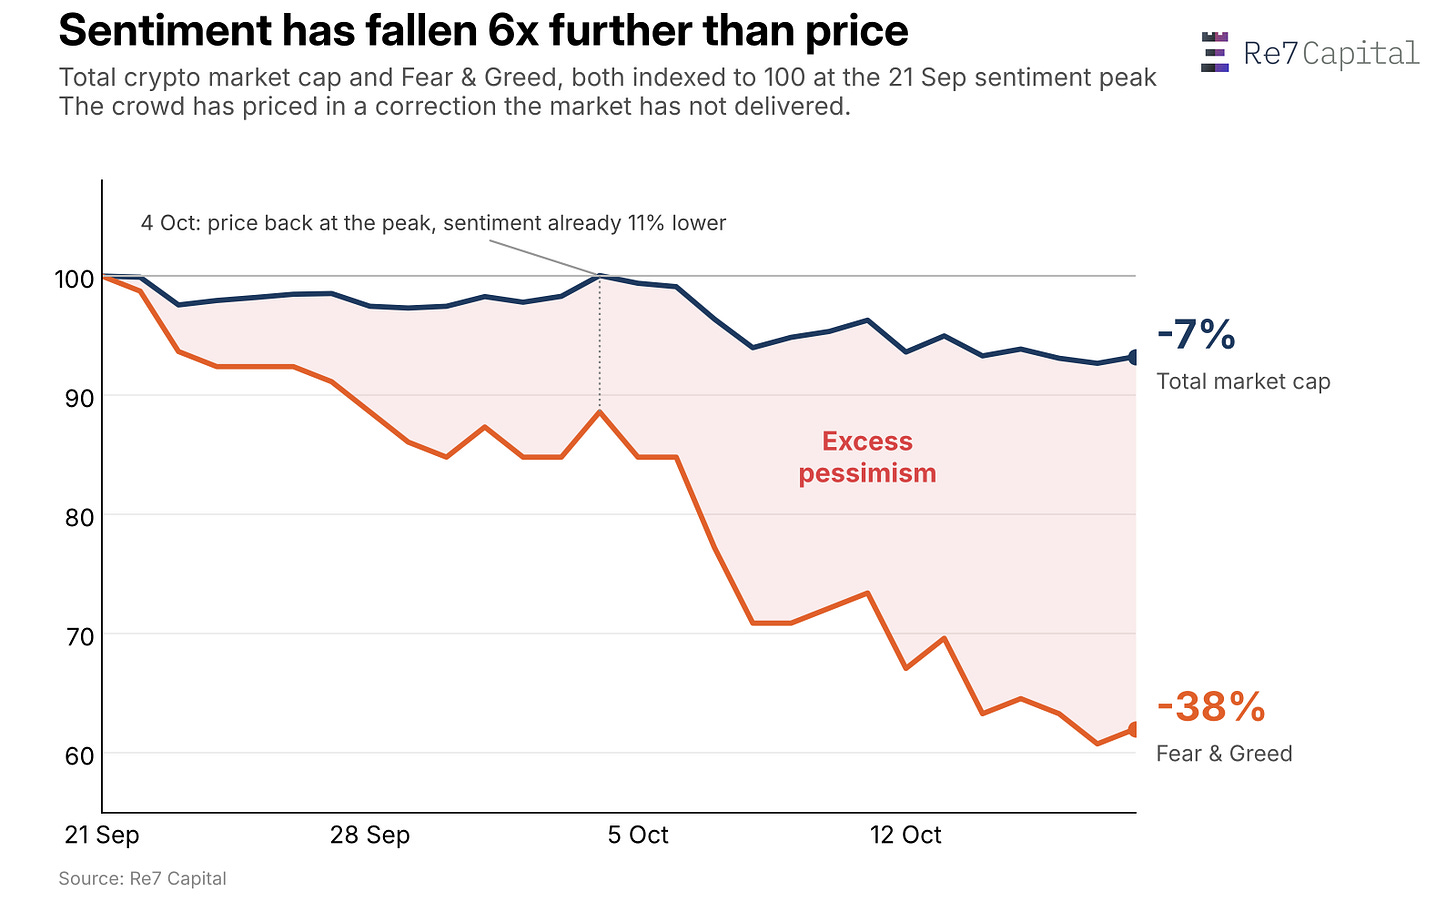
The latest Fear & Greed reading of 20 signals Extreme Fear, despite prices holding relatively firm. A similar divergence is visible in equities, with the S&P 500 just 2% below its record closing high despite sentiment reaching Extreme Fear.
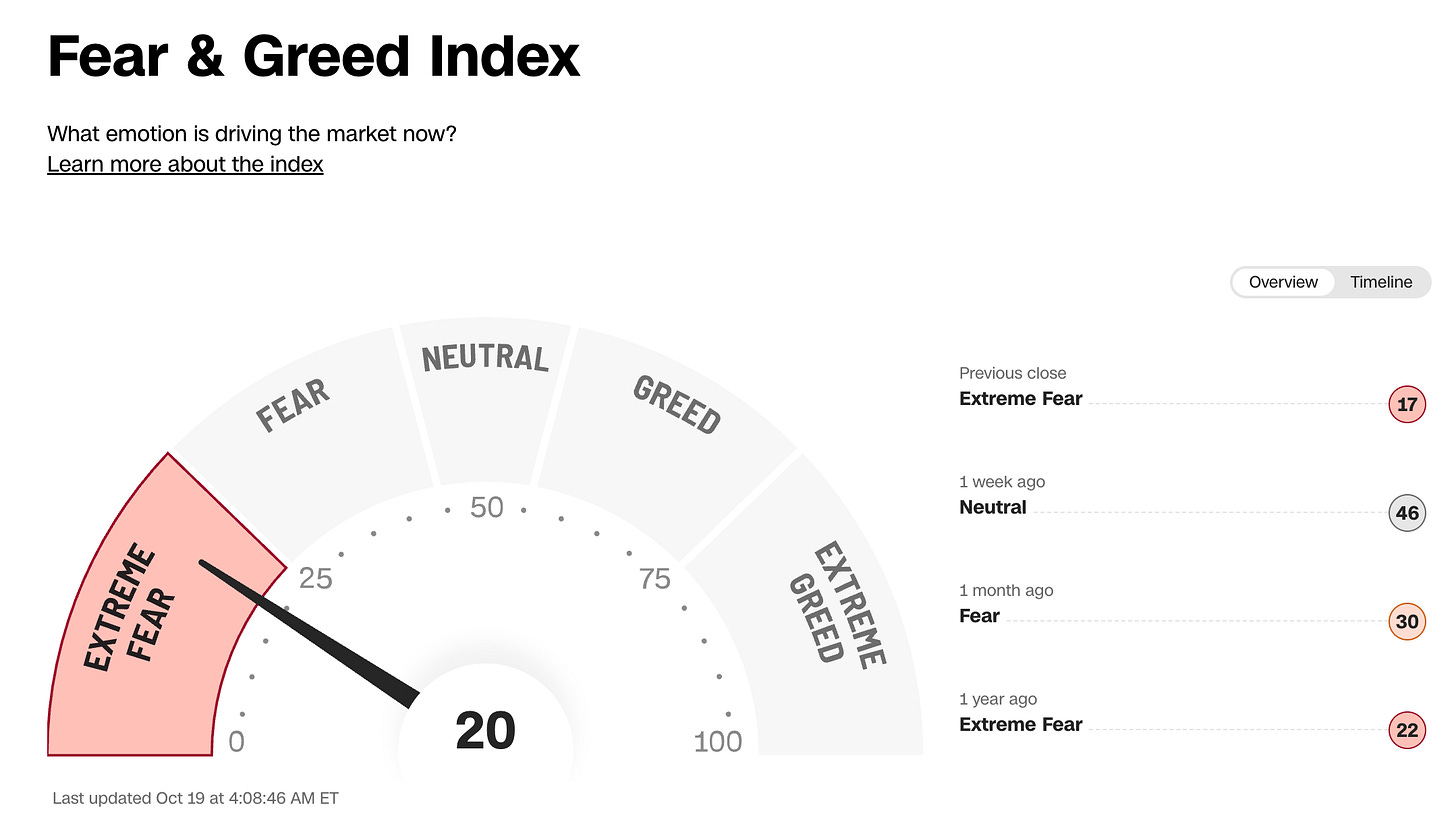
CNN S&P Fear & Greed Index.
Investors are pricing in a much larger correction than markets have delivered. With positioning already cautious, there is less complacency to unwind and greater scope for an upside surprise as confidence returns.
Crypto is also showing relative strength, outperforming the Nasdaq 100 by more than 2% last week.
This is not simply a market holding its ground in nominal terms, but one beginning to outperform other risk assets.
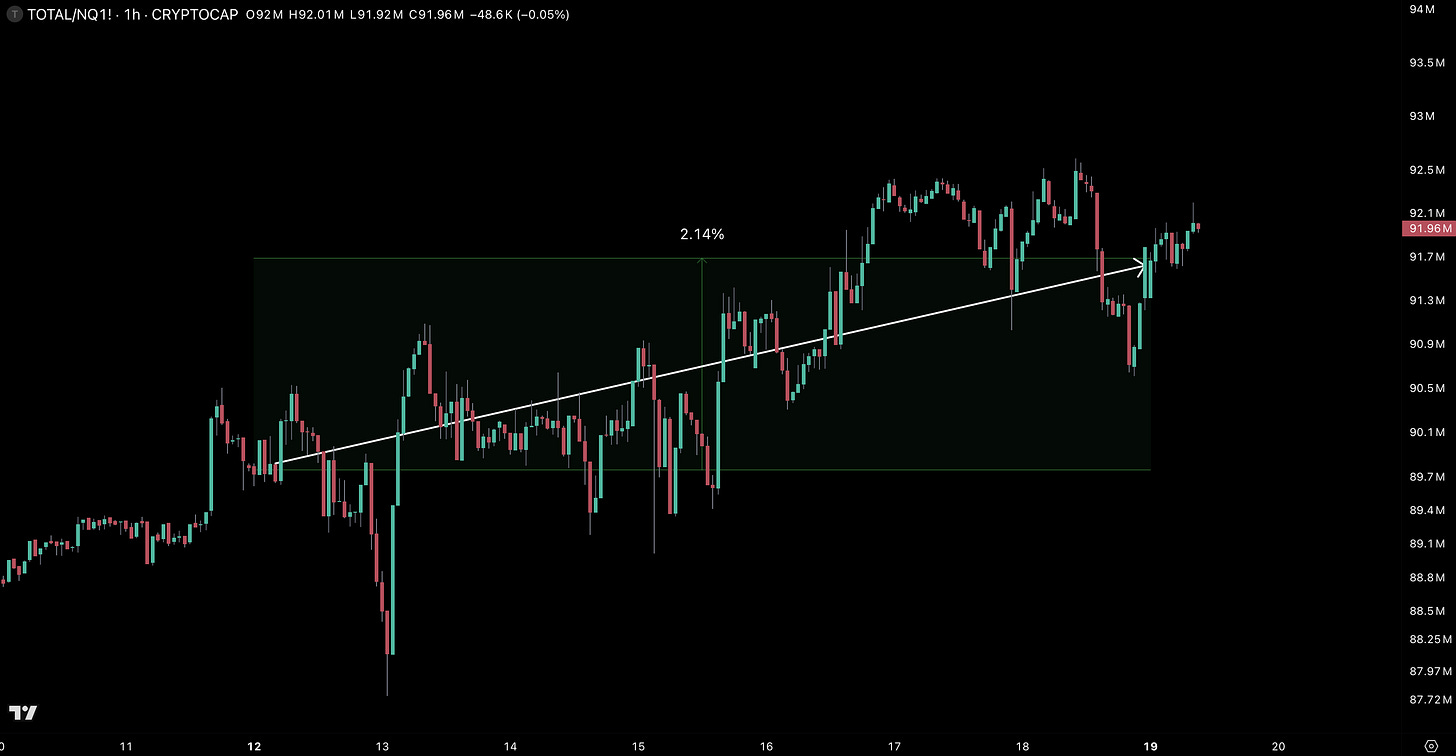
The crypto/NASDAQ ratio over the past week.
Looking Ahead
China’s Q3 GDP growth of 4.5% beat expectations, providing some support for risk assets. This follows efforts by Chinese authorities to stabilise domestic equities through selling restrictions and state-backed purchases.
Nevertheless, markets may remain nervous ahead of the US midterms on 3 November, with hyperscaler earnings over the next two weeks likely to be an important catalyst.
Earnings are likely to remain strong, reassuring investors that growth is holding up and AI investment continues to be supported by underlying demand.
This could mark a turning point in market momentum, particularly as the midterms approach and another source of uncertainty is removed.
The midterms should then remove another source of uncertainty, allowing investors to focus more clearly on year-end positioning.
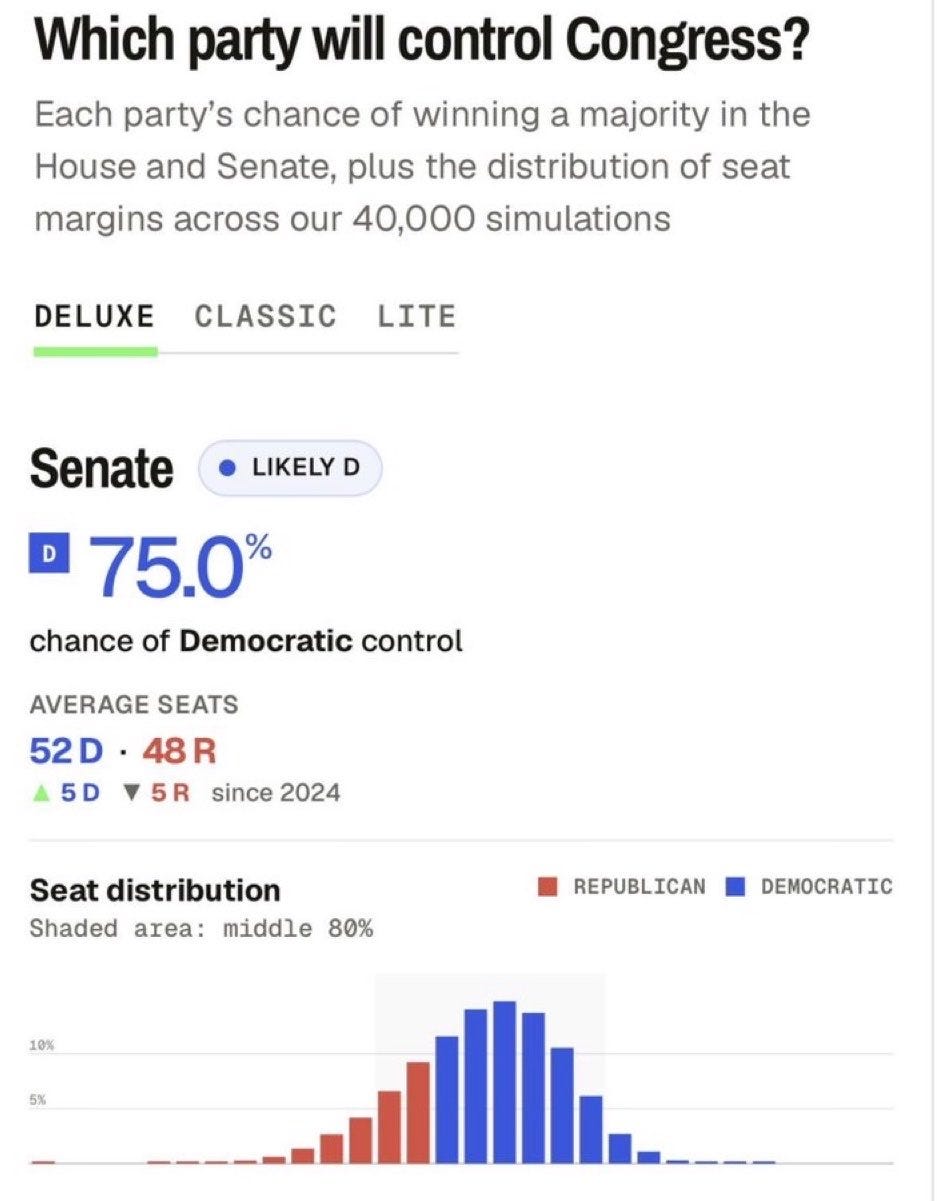
Nate Silver’s latest midterm election forecast.
For now, the combination of resilient prices, extreme pessimism and improving relative strength is constructive.
Markets are being given reasons to fall, but increasingly refusing to do so. And that’s worth paying attention to.
State of Yields
Yields have expanded slightly across the board in light of recent market volatility:
Stablecoin lending yields:
~3.84% on Aave (USDC) — 20 bps lower than last week.
~4.85% on Aave (USDe) — 200 bps lower than last week.
~5.18% on Maple (syrupUSDC) — 6 bps lower than last week.
Fixed-rate DeFi lending: yield premium in fixed markets:
Pendle sUSDAi: ~8.76% (Oct 2026 – Feb 2027 maturities).
sUSDe: ~5.25% —5 bps lower than last week.
ETH yield benchmarks:
Lido staking: ~2.22% — 4 bps higher than last week.
About Re7
Re7 Capital is a research-driven digital asset investment firm specialising in DeFi yield and liquid alpha strategies.
Re7 Labs is an on-chain asset management and risk curation firm bringing institutional-grade rigour to DeFi.
Disclaimers
The content is for informational purposes only. None of the content is meant to be investment advice. Use your own discretion and independent decision regarding investments. The opinions expressed in all Re7 public research articles are the independent opinions of the authors at the time of publication and not the opinions of the affiliates of Re7.
Please see here for full disclaimers.