The Weekly: Crypto Defies the Hikes
SEP 14, 2026
Robinhood Chain and Stonk.fun activity cools as the Clarity Act nears a Senate vote, while crypto markets show resilience against rising rate-hike bets.
Re7 Celebrates 5 Years. In recognition, The Hedge Fund Journal featured Re7 Capital. Read the full profile to find out how we think about risk in DeFi, and why we treat it closer to a credit discipline than a trading strategy.
—
Evgeny Gokhberg joined 1000x Podcast: What It’s Like Running A Billion-Dollar Market-Neutral Fund In Crypto.
—
We are hiring!
Senior Legal Counsel - Apply here.
Re7 Labs x Kamino: Introducing the Plume Vaults.
Re7 Labs, in partnership with Kamino, launched a dedicated Plume Vaults market - bringing curated lending and borrowing to a new class of onchain products.
Re7's OP Morpho WETH vault was integrated by AlchemixFi.
Weekly Summary
We cover:
Robinhood Chain activity rolling over after the stock-token/memecoin surge
The latest Clarity Act update and path to passage
Why crypto is holding up despite rising rate-hike expectations
Robinhood Mania Fades
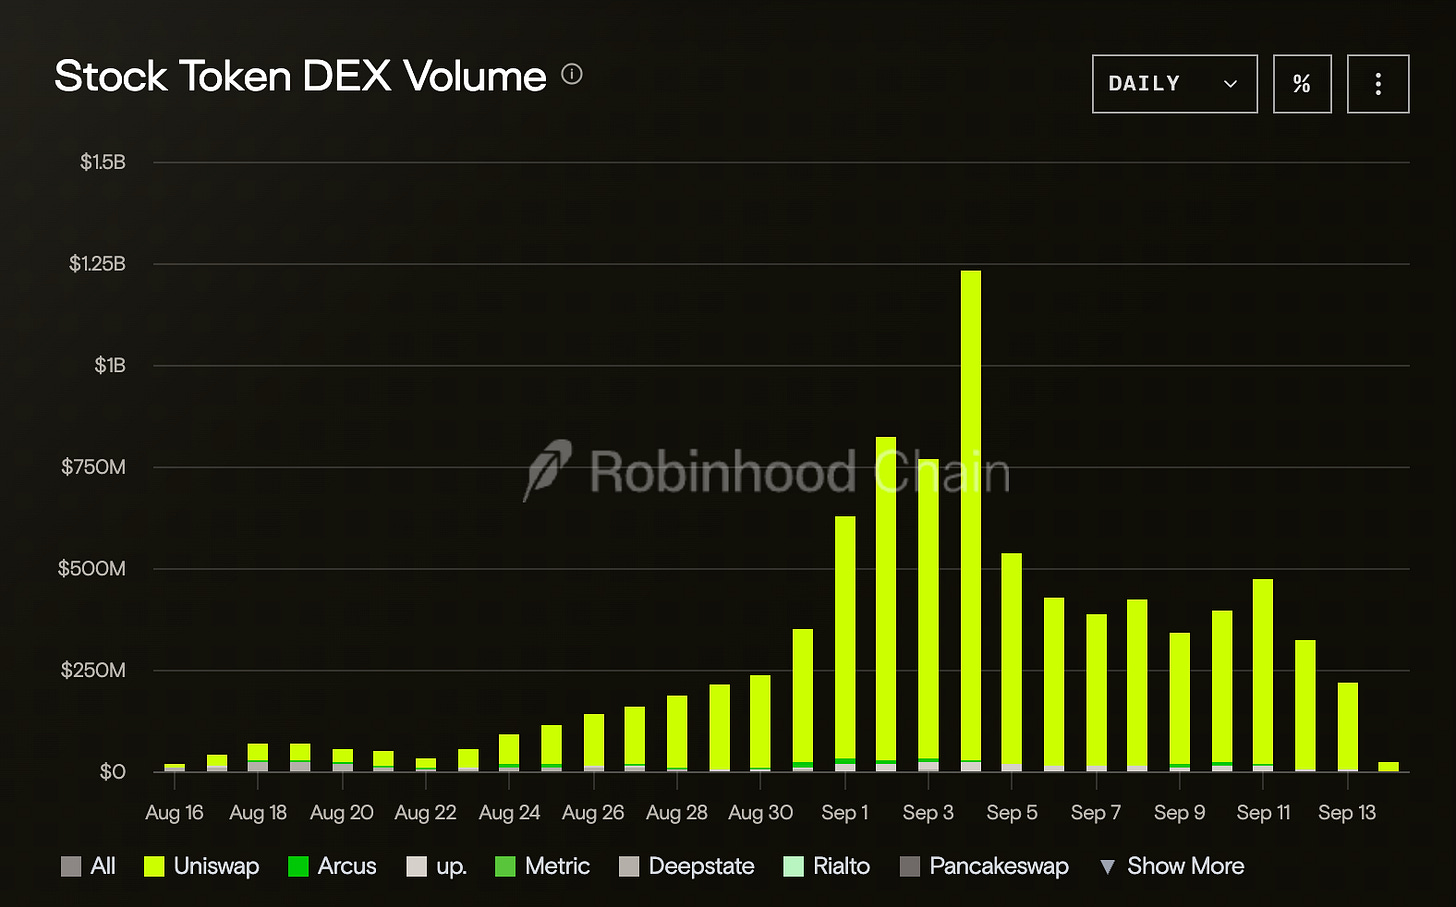
Robinhood Chain saw a sharp acceleration in activity through late August and early September, driven largely by meme coins pairing against tokenised stocks.
That activity is now rolling over. Stock-token DEX volume is down 7% over the past week and daily volume has fallen significantly from the early-September peak.
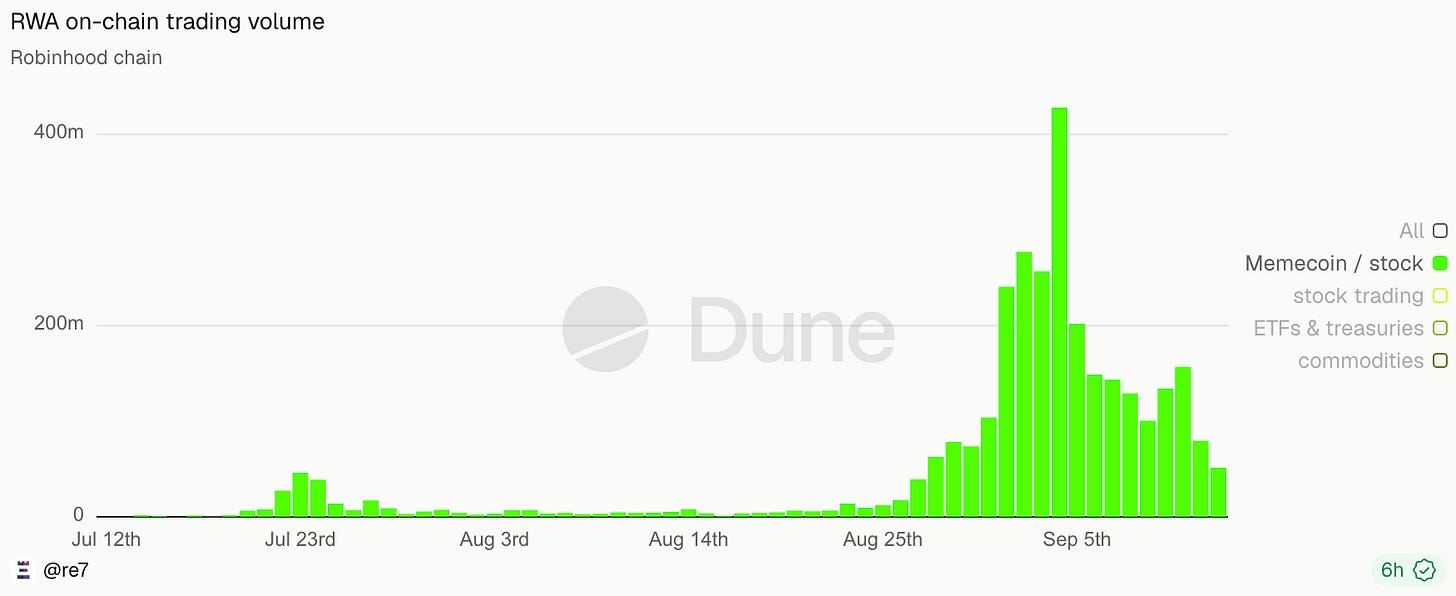
The same is visible in meme coin/stock trading. Daily volume peaked above $400m in early September but has since fallen back towards ~$50m.
The more important KPI is underlying tokenised value. This increased rapidly from ~$50m at the end of August to ~$150m by early September, but has since flattened around ~$165–170m.
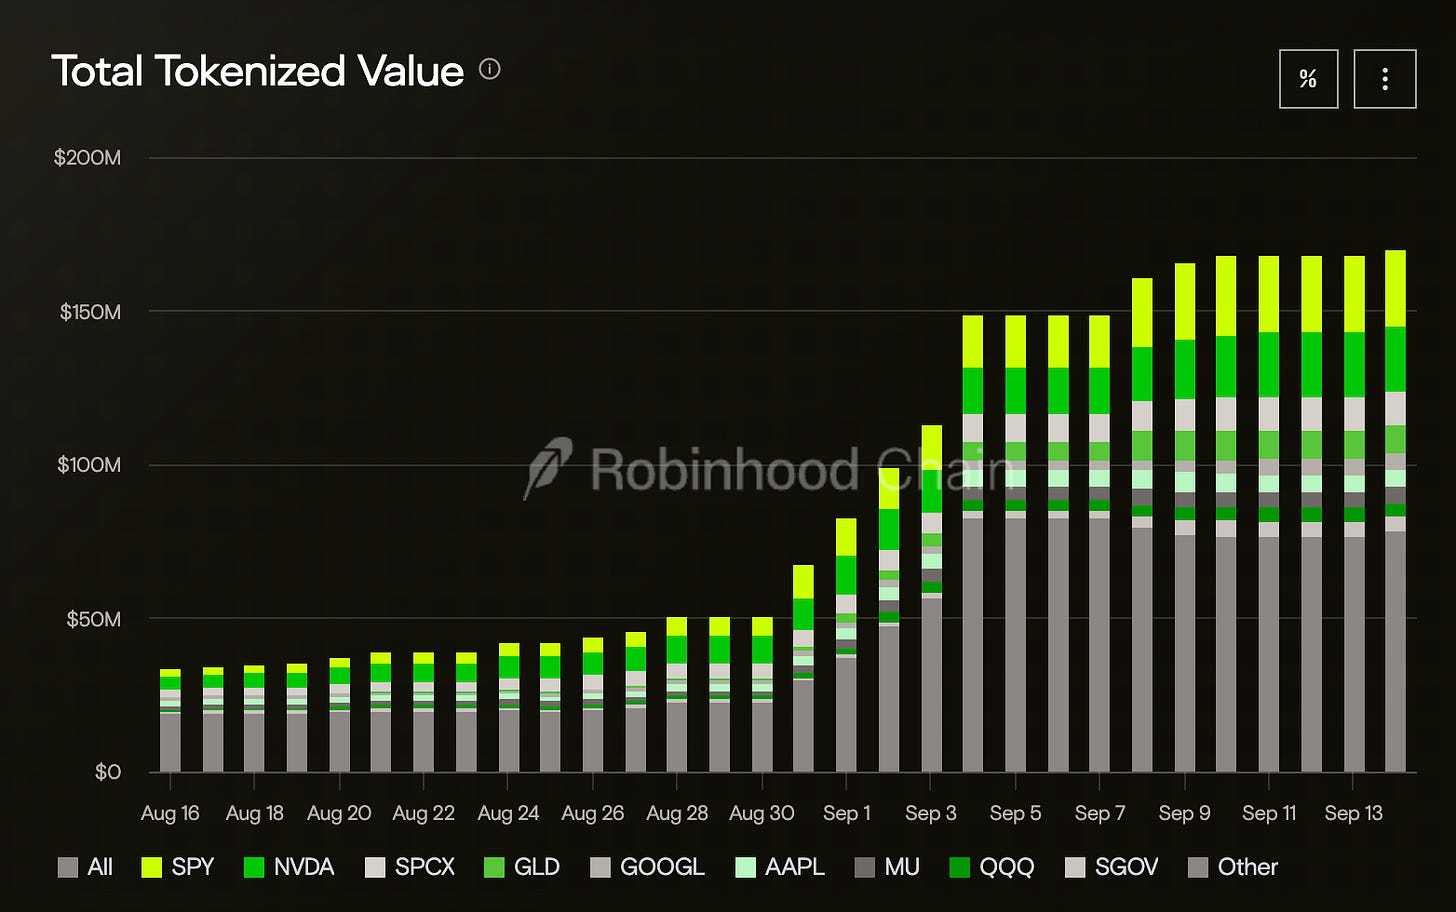
This suggests the recent spike in activity was at least partly speculative.
Trading volumes increased far faster than the amount of assets actually being brought onchain, and volumes are now falling while tokenised value has stopped accelerating.
Thin stock-token supply and limited minting hours allowed speculative demand to push tokens above the underlying shares, with premiums collapsing once new supply entered.
While this left late buyers with losses and cooled speculation, the mania also catapulted Robinhood’s tokenised shares into a major onchain distribution channel.
Stonk.fun Captures The Same Trade
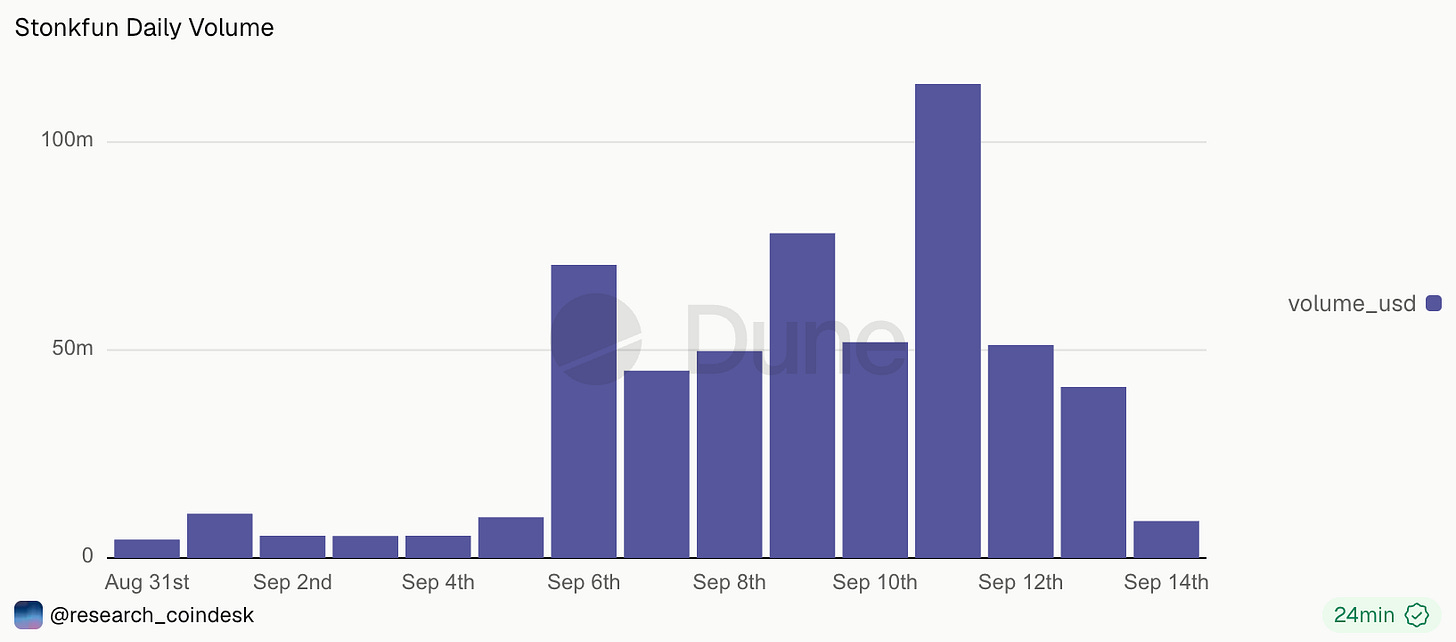
The stock-paired memecoin mania was not limited to Robinhood. Stonk.fun effectively brought the Pons model to Solana, pairing newly launched tokens against tokenised stocks and giving Solana users another distribution channel into the same trade.
It initially captured the same surge in attention, but its core KPIs are now rolling over alongside Robinhood activity. That supports the view that both platforms benefited from the same stock/memecoin mania rather than independent structural growth.
Clarity Act Update
Senate Republicans have released what they describe as the final Clarity Act draft ahead of Tuesday’s cloture vote, including 126 changes requested by Democrats.
The biggest compromise is on ethics. Trump has accepted most restrictions on crypto activity for elected officials and their spouses, removing a key Democrat objection.
The draft also introduces an 18-month Treasury “circuit breaker” on stablecoin rewards if they cause significant community-bank deposit outflows, addressing another major sticking point.
Tuesday’s cloture vote requires 60 votes, meaning at least seven Democrats or independents are needed if all 53 Republicans support it.
Even if it passes, the timeline is tight. The bill still needs Senate passage and House approval before the midterms. Polymarket odds of passage this year have risen from ~22% to ~32% on Monday morning.
Market Update
Last week’s inflation prints pushed markets further towards a Fed hike, with around 3.5–4 rate hikes now priced by mid-2027. That is a roughly 200bp swing from the cuts expected at the start of the year and, normally, a clear headwind for crypto.
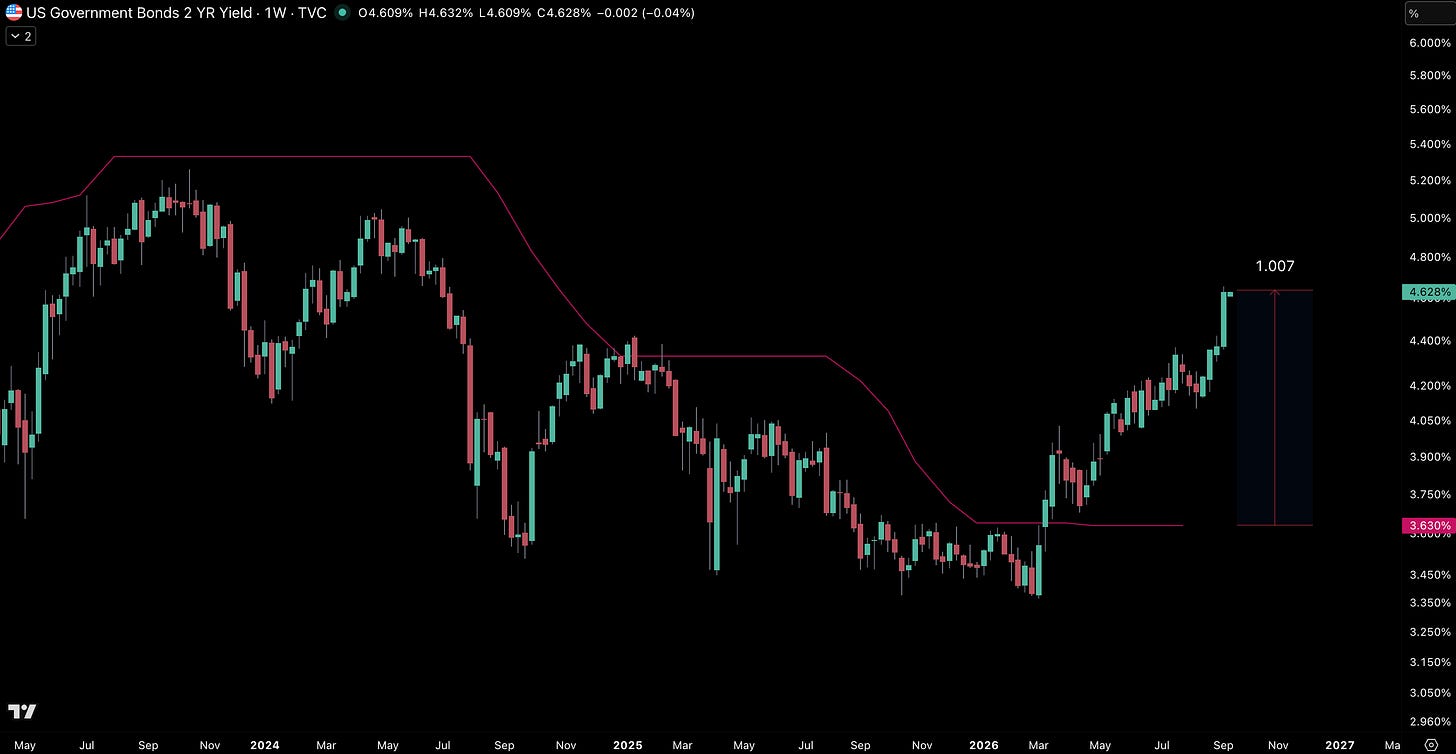
2-year yield is ~100bp above Fed funds (pink), reflecting significant tightening already priced.
But it is not as simple as hikes = bad. The 2-year yield is already ~4.6% versus Fed funds at ~3.6%, meaning markets have moved well ahead of the Fed.
The current curve is consistent with inflation staying around the high-2s/low-3s, meaning it likely needs to reaccelerate to drive another hawkish repricing.
The economy is also less rate-sensitive than in 2022. The capex boom is being led by large, cash-generative technology companies, while underlying S&P 500 earnings grew ~32% YoY in Q2.
There are also few signs of broad speculative excess in equities with this strong earnings growth.
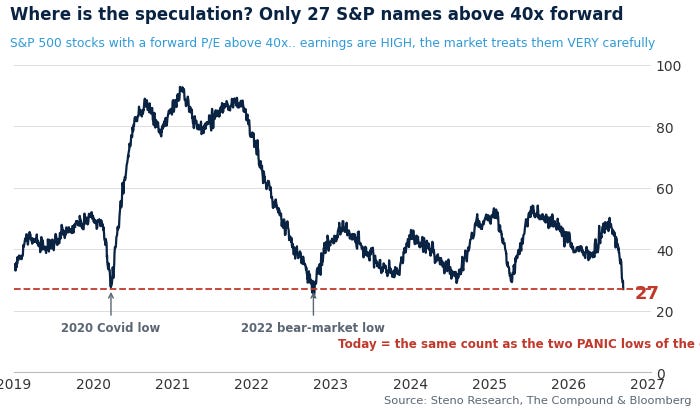
Another 25–100bp hurts rate-sensitive areas, but does little to slow the investment driving growth.
If yields are close to topping and the curve bull steepens, financial conditions can ease even while the Fed hikes. Bessent also likely wants a weaker dollar to support US exports and rebalance trade, which would provide another tailwind to global liquidity and crypto.
We believe this helps explain why markets have remained resilient despite rising hike expectations. What matters is whether inflation, yields and the dollar deteriorate beyond what is priced, while Clarity provides a separate catalyst for crypto.
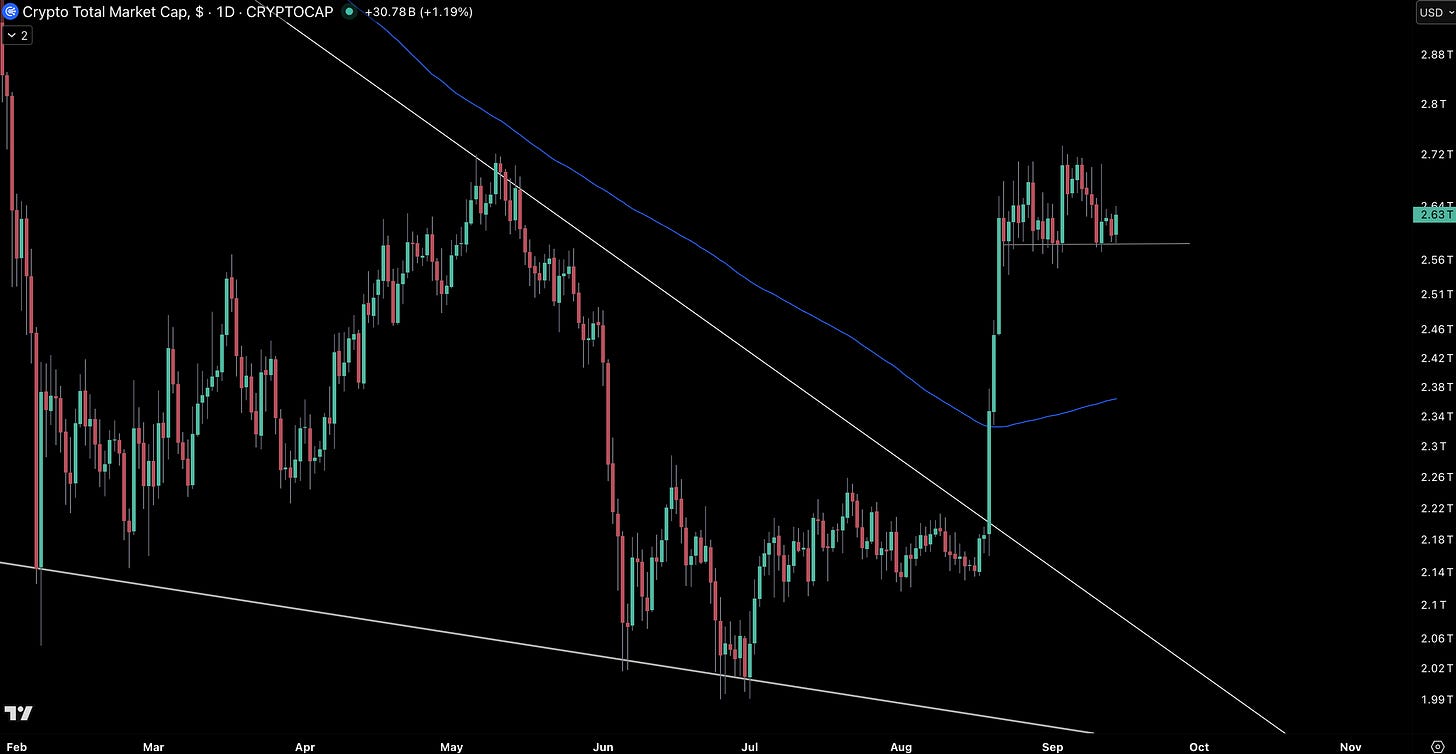
Global crypto market capitalisation index (Daily; $).
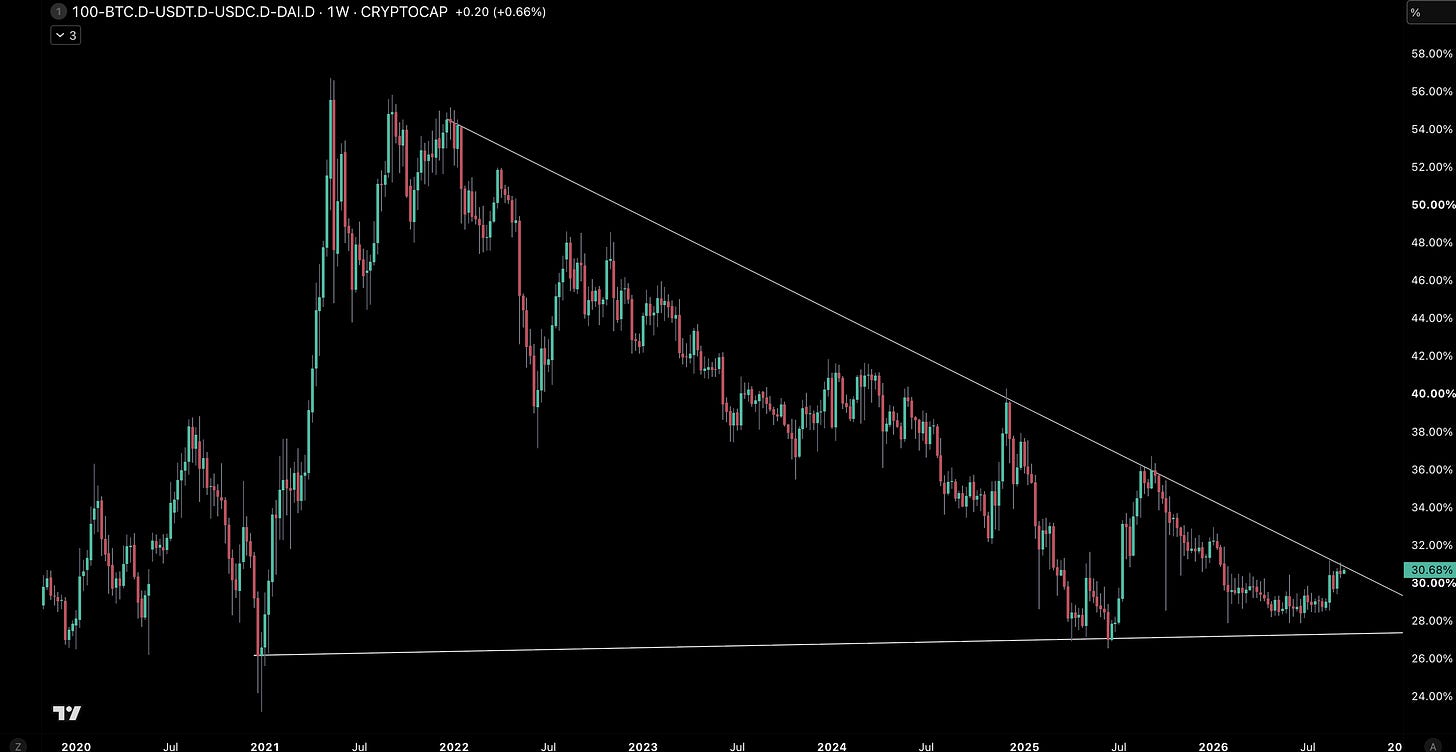
Even more unusually, altcoin market dominance is looking to break out while rate-hike pressures mount.
Seeing breadth expand into alts despite that pressure suggests the market is not yet treating the expected tightening as a major liquidity shock.
Finally, further signals of the same are found in ratios like crypto/NASDAQ, which is up +3% this week.
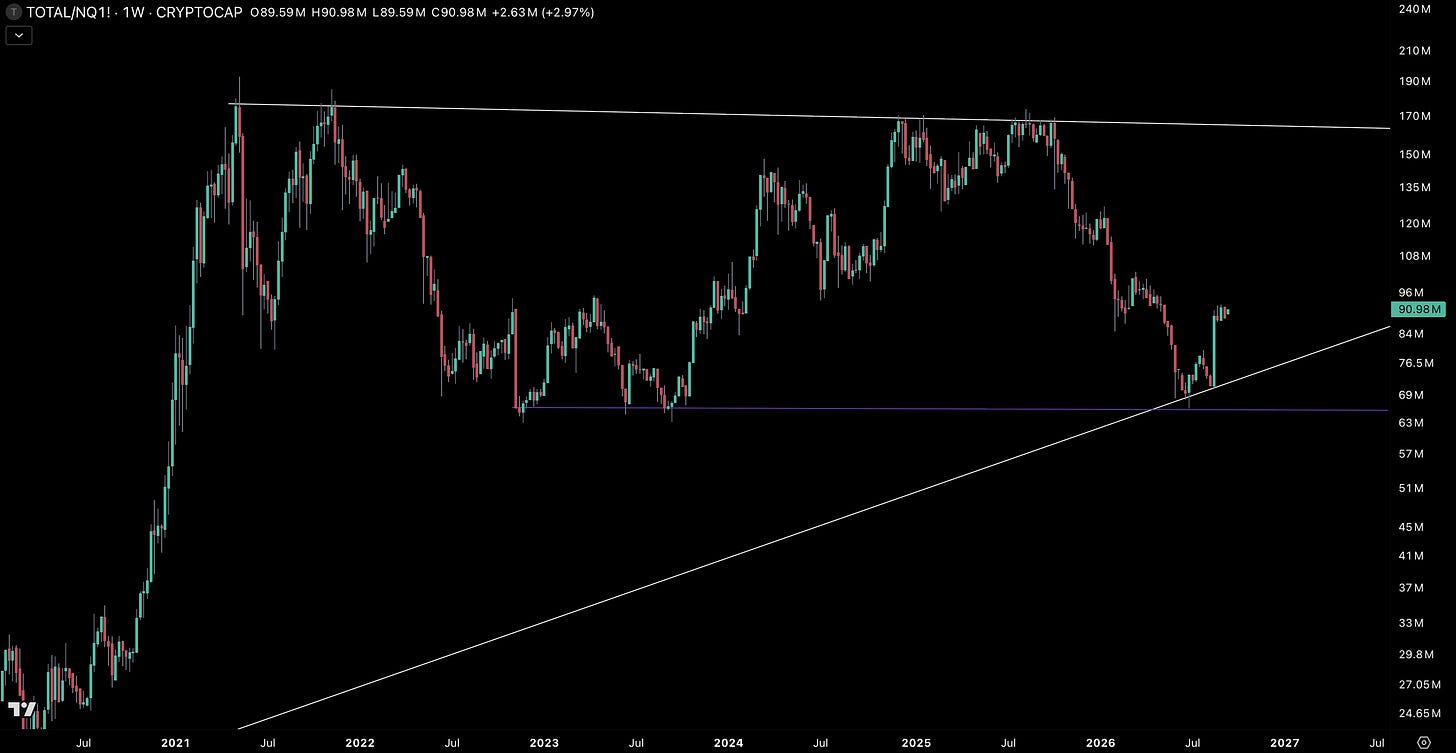
Crypto/NASDAQ futures ratio (weekly).
The broader message is that the market is behaving very differently from a conventional tightening regime.
State of Yields
Yields have expanded slightly across the board in light of recent market volatility:
Stablecoin lending yields:
~3.62% on Aave (USDC) — -3 bps from last week.
~4.85% on Aave (USDe) — same as last week.
~4.96% on Maple (syrupUSDC) — 4bp lower than last week.
Fixed-rate DeFi lending: yield premium in fixed markets:
Pendle sUSDAi: ~9.75% (Oct 2026 – Feb 2027 maturities).
sUSDe: ~8.15% — 300 bps higher than last week.
ETH yield benchmarks:
Lido staking: ~2.24% — 1 bps higher than last week.
About Re7
Re7 Capital is a research-driven digital asset investment firm specialising in DeFi yield and liquid alpha strategies.
Re7 Labs is an on-chain asset management and risk curation firm bringing institutional-grade rigor to DeFi.
Disclaimers
The content is for informational purposes only. None of the content is meant to be investment advice. Use your own discretion and independent decision regarding investments. The opinions expressed in all Re7 public research articles are the independent opinions of the authors at the time of publication and not the opinions of the affiliates of Re7.
Please see here for full disclaimers.